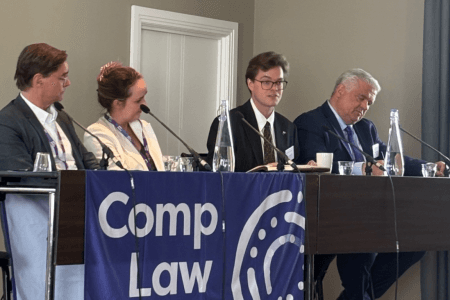
On Tuesday, 29 April, Andrew Hill, Senior Policy Adviser, AmCham EU represented the organisation at CompLaw's Foreign Direct Investment (FDI) Regimes & Foreign Subsidies Regulation conference. Joining the panel on the EU foreign direct investment screening mechanism, Mr Hill stressed the need to align FDI screening frameworks across borders and to ensure that FDI screening is focused on transactions with clear national security concerns. He also underlined the importance of predictability for businesses operating in the Single Market. The Foreign Investment Screening Regulation, if designed correctly, could make a significant impact in safeguarding security while preserving Europe's openness to global investment.
Highlighting the need for predictable investment policies
Related items
Position Paper
28 Oct 2026
Industry calls for ambitious tax simplification
AmCham EU has joined 22 other business, financial and professional associations in calling on Member States to reach agreement on the Commission’s Tax Simplification Package. The measures could save businesses operating in Europe around €8 billion a year, money currently absorbed by complexity rather than invested in growth. Tax collected only to be refunded and withholding taxes that hinder investment in the Single Market add costs without strengthening the tax base. Europe has already strengthened its tax framework, so simplification can go ahead without weakening enforcement. Agreement will only matter if the ambition of the package survives the negotiations. Read the full joint statement here.
Position Paper
26 Oct 2026
Digital euro: getting the final design right

Position Paper
25 Sep 2026
Closing the gap between customs and VAT rules
The reform of the Union Customs Code changes who is treated as the ‘importer’ when a non-EU company uses an indirect customs representative. That creates a problem under the EU VAT Directive, which links import VAT deduction to being identified as the importer or consignee. In practice, the non-EU company may no longer meet that requirement, while the customs representative may not qualify for the deduction either.
That could leave import VAT irrecoverable and create uncertainty for businesses using established import models. The Commission should ensure that the non-EU principal can still be identified in customs data for VAT purposes and fix the mismatch between the UCC and the VAT Directive.
Learn more about what changes are needed to keep import VAT deductibility workable under the new customs framework.
Policy priorities
Insights and advocacy driving Europe’s policy agenda. Our priorities support growth, innovation and a stronger transatlantic economy.
Membership
Connecting business and policymakers to strengthen the voice of American companies in Europe.